Oramed Pharmaceuticals (ORMP) (~$85MM market cap) is a biotechnology company that has a platform designed to reformulate injections/vaccines into orally administered drugs. Their furthest along asset is ORMD-0801, orally administered insulin for diabetes patients, it recently did not meet its primary or secondary end points in their Phase 3 trial. Previously, Oramed had been guiding to a 2025 anticipated FDA approval for ORMD-0801, given this sudden failure, the stock naturally dropped considerably on the news. Then on 2/9, the company announced they were "examining the Company's existing pipeline and conducting a comprehensive review of strategic alternatives focused on enhancing shareholder value." In addition to the diabetes trial, Oramed does have an ongoing Phase 2 trial for ORMD-0801 in patients with NASH, a liver disease without an approved FDA treatment. Lastly, Oramed owns 63% of Oravax, a joint venture that is pursuing an orally administered COVID-19 vaccine and other applications of an oral vaccine.
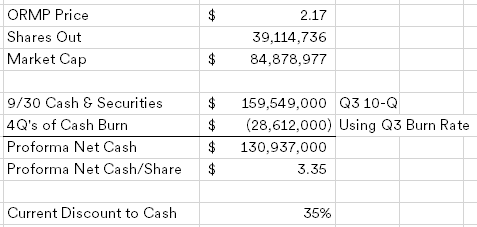
Doing the same math as MGTA, below I took the 9/30 cash and subtracted four quarters of their cash burn (including the $1MM/quarter in interest income) since they're earlier in their busted biotech lifecycle, i.e. they haven't let go of their workforce (couldn't find the employee count in their filings, but Oramed only has 16 employees on LinkedIn) and haven't shutdown their other trials. On the plus side, they only have a minimal lease obligation here, making it a bit of a cleaner balance sheet.
Disclosure: I own shares of ORMP
